Read our market review and find out all about our theme of the week in MyStratWeekly and its podcast with our experts Axel Botte, Aline Goupil-Raguénès and Zouhoure Bousbih.
Listen to Axel Botte’s and Aline Goupil-Raguénès' podcast (in French only)
Podcast slides (in French only)
Download the Podcast slides (in French only)Topic of the week: Eurozone: The Residential Real Estate Market at a Turning Point
- After four consecutive quarters of decline, residential property prices in the Eurozone have seen a slight increase. The situation remains very contrasted between countries;
- The rate cuts implemented and anticipated by the ECB have resulted in a slight easing of mortgage rates;
- This is accompanied by a moderate increase in loans granted to households for house purchase;
- According to the ECB survey, household demand for loans is expected to rebound significantly due to interest rate cuts and improved outlooks in the real estate market;
- At the same time, household confidence has improved, although it remains below its long-term average, following the gradual recovery from past losses in purchasing power;
- The anticipated rate cuts by the ECB, the continued gains in purchasing power, and a labor market that is expected to remain generally favorable support the case for a continued moderate increase in property prices in the Eurozone.
Market review: The Fed, inflation, and the dollar
- Powell is not in a hurry to lower interest rates;
- U.S. inflation rose to 2.6% in October, and producer prices are tightening;
- The spread between the Treasury note and the Bund has reached 210 basis points;
- Profit-taking on European stocks; Asia is down sharply.
Axel Botte’s and Aline Goupil-Raguénès' podcast:
- Review of the week – Financial markets, US inflation, the superstar Dollar;
- Theme – Residential real estate market in the eurozone.
Chart of the week
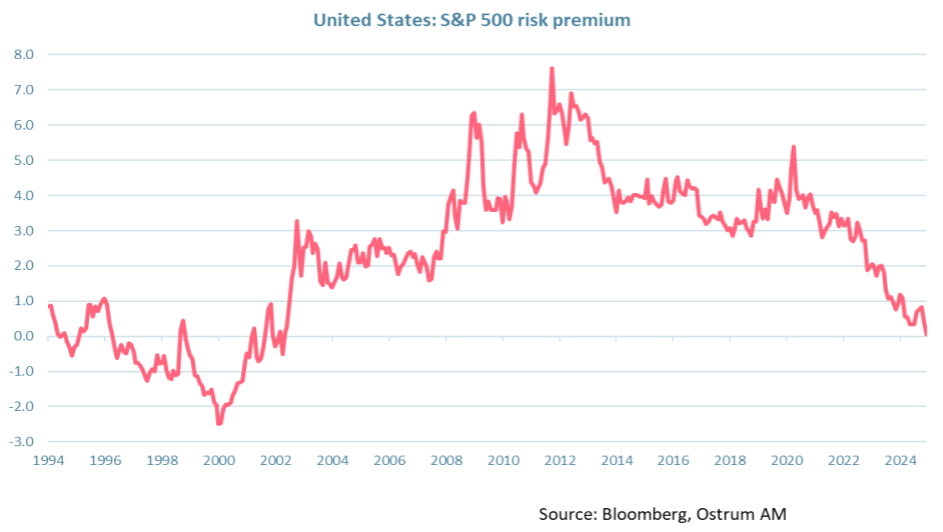
The equity risk premium has fallen to 0%.
This simple model corresponds to the difference between the expected earnings yield over 12 months on the S&P 500 index and the yield on the 10-year Treasury note. This premium was about 4% between 2012 and 2020, partly due to very low long-term rates resulting from quantitative easing (QE).
The rise in long-term rates has therefore contributed to reducing this premium, but the significant increase in stock prices has outpaced earnings growth. This premium recalls the irrational exuberance described by Greenspan as early as 1996, which led to the bursting of the TMT bubble in 2000.
Figure of the week
1.3%
The European commission published its GDP forecast for the euro area for 2025, which is expected at 1.3%. It highlights an increase in uncertainty and downside risks to growth, particularly due to the potential rise of protectionist measures.
MyStratWeekly : Market views and strategy
MyStratWeekly – November 19th 2024-
Axel Botte Head of markets strategy
-
Zouhoure Bousbih Emerging countries strategist
-
Aline Goupil-Raguénès Developed countries strategist